
Introduction to Business Loans
Business Loans and managing a business requires financial resources. Whether you are launching a startup, expanding an existing company, purchasing equipment, or managing daily operating expenses, having access to sufficient capital is essential. However, many business owners do not have enough personal savings to cover every financial requirement. This is where business loans become an important financing option.
Business loans are financial products that allow companies to borrow money from banks, credit unions, online lenders, and other financial institutions. Businesses can use borrowed funds for different purposes, including purchasing inventory, hiring employees, investing in technology, expanding operations, and improving cash flow.
Choosing the right business loan can help entrepreneurs achieve their financial goals without immediately using all their available capital. However, borrowing money also creates repayment responsibilities, interest costs, and potential financial risks.
Understanding different loan types, eligibility requirements, interest rates, repayment terms, and application procedures can help business owners make better financial decisions.
In this comprehensive guide, we will explain how business loans work, explore different financing options, discuss their advantages and disadvantages, and provide practical tips for choosing suitable business financing.
What Are Business Loans?
Business loans are funds borrowed by companies or entrepreneurs from financial institutions or other lenders to support business activities.
The borrower receives an agreed amount of money and repays it according to specific terms. These terms usually include the repayment period, interest rate, payment schedule, and additional fees.
Business loans can be used for several purposes, such as:
- Starting a new business.
- Purchasing equipment and machinery.
- Buying inventory and raw materials.
- Hiring additional employees.
- Expanding business operations.
- Opening new locations.
- Managing short-term cash flow problems.
- Renovating offices or commercial properties.
- Refinancing existing business debt.
Different businesses require different types of financing. A small retail shop may need a short-term loan to purchase inventory, while a manufacturing company may require long-term financing to purchase expensive equipment.
Understanding your financial requirements is the first step toward choosing an appropriate loan.
Different Types of Business Loans
Financial institutions offer several types of business loans based on business requirements, creditworthiness, and repayment capacity.
1. Term Loans
A term loan provides a fixed amount of money that the borrower repays over an agreed period.
These loans may have fixed or variable interest rates depending on the lender and financing agreement.
Businesses commonly use term loans for equipment purchases, expansion projects, renovations, and other major investments.
2. Small Business Loans
Small business loans are financing products designed for small companies and entrepreneurs.
They can support working capital requirements, inventory purchases, marketing activities, and operational expenses.
Eligibility requirements vary depending on the financial institution and the business’s financial history.
3. Startup Business Loans
Startup business loans provide funding to entrepreneurs who want to establish new businesses.
These loans can help cover initial expenses such as equipment, registration, product development, marketing, and working capital.
However, obtaining financing for a new business can be challenging because startups often have limited financial records and no established repayment history.
4. Equipment Financing
Equipment financing allows businesses to purchase machinery, computers, vehicles, and other essential equipment.
The equipment being financed may serve as collateral, depending on the agreement.
This financing option can help companies obtain necessary assets without paying the entire purchase price upfront.
5. Business Lines of Credit
A business line of credit provides access to an approved borrowing limit.
Businesses can withdraw funds when needed and generally pay interest on the amount used rather than the entire available limit.
It can be useful for managing temporary cash shortages, seasonal expenses, and unexpected operational costs.
6. Invoice Financing
Invoice financing allows businesses to access money tied up in unpaid customer invoices.
Instead of waiting for customers to complete their payments, a company receives an advance against eligible invoices through a financing provider.
This can improve short-term liquidity for businesses that regularly provide services or products on credit.
Fees, advance rates, and collection arrangements vary by provider.
7. Commercial Real Estate Loans
Commercial real estate loans help businesses purchase, construct, or renovate commercial properties.
Companies may use this financing to acquire offices, warehouses, retail locations, and manufacturing facilities.
These loans generally involve larger amounts and longer repayment periods.
8. Microloans
Microloans are relatively small financing arrangements designed to support entrepreneurs and small businesses.
They may be offered by nonprofit organizations, development institutions, community lenders, and other eligible financing providers.
Microloans can help businesses that require limited capital to purchase equipment, supplies, or inventory.
Secured vs. Unsecured Business Loans
Business loans can also be categorized according to whether collateral is required.
Secured Business Loans
Secured business loans require the borrower to provide an asset as collateral.
Examples include commercial property, vehicles, machinery, or other acceptable assets.
If the borrower fails to meet repayment obligations, the lender may have the legal right to recover the outstanding amount through the collateral, subject to the loan agreement and applicable law.
Advantages include potentially lower interest rates, access to larger loan amounts, and longer repayment periods.
However, the main disadvantage is the risk of losing pledged assets if the borrower defaults.
Unsecured Business Loans
Unsecured business loans do not generally require specific collateral.
Instead, lenders evaluate factors such as credit history, revenue, business performance, financial statements, and repayment capacity.
These loans may offer faster access to funding, but they can involve higher interest rates and stricter eligibility requirements.
Some unsecured loans may still require a personal guarantee.
How Do Business Loans Work?
The business loan process usually involves several stages.
Step 1: Determine Your Financing Needs
Identify why your business requires additional funding.
Calculate the amount needed and prepare a clear explanation of how the money will be used.
Step 2: Research Available Lenders
Compare financing options from banks, credit unions, online lenders, and other financial institutions.
Review interest rates, repayment conditions, processing fees, and eligibility requirements.
Step 3: Submit a Loan Application
Complete the lender’s application process and provide the requested business and financial information.
Step 4: Financial Evaluation
The lender evaluates the application to determine whether the business can repay the borrowed amount.
This may include reviewing credit history, revenue, existing debts, financial statements, and collateral.
Step 5: Loan Approval and Agreement
If the application is approved, the lender provides the loan terms.
Carefully review the interest rate, total repayment amount, payment schedule, fees, and any collateral requirements before signing.
Step 6: Receive the Funds
After completing the required documentation, the lender releases the approved funds according to its procedures.
Step 7: Repay the Loan
Make payments according to the agreed schedule.
Consistent repayment helps businesses maintain a positive financial relationship with lenders.
Business Loan Interest Rates and Repayment Terms
Interest rates represent the cost of borrowing money.
The rate offered by a lender depends on several factors, including:
- Business credit history.
- Personal credit history, where relevant.
- Loan amount.
- Repayment duration.
- Business revenue.
- Existing financial obligations.
- Collateral availability.
- Market and economic conditions.
Business loans may have fixed or variable interest rates.
Fixed Interest Rate: The interest rate remains unchanged throughout the agreed period, providing more predictable payment amounts.
Variable Interest Rate: The interest rate may change according to an agreed benchmark or lending terms, which can affect future payments.
Repayment periods also vary. Short-term loans may require repayment within months, while larger business loans can extend over several years.
Before borrowing, calculate the total repayment cost rather than comparing interest rates alone. Processing charges, service fees, early repayment conditions, and other costs can affect the overall expense.
Business Loan Eligibility Requirements
Loan eligibility requirements vary among lenders and financing products.
However, many financial institutions evaluate the following factors.
Credit Score
A credit score helps lenders assess the borrower’s credit history and repayment behavior.
A stronger credit profile may improve the chances of approval and access to competitive financing terms.
Business Revenue
Lenders often review business income to determine whether the company generates sufficient money to support loan repayments.
Business History
Established businesses may have an advantage because they can provide historical financial statements and operating records.
However, some lenders offer financing options specifically designed for startups.
Financial Statements
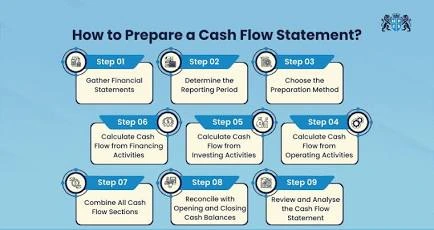
Lenders may request income statements, balance sheets, cash flow statements, and bank statements.
These documents help evaluate the company’s financial position.
Business Plan
Startups and expanding businesses may need a detailed business plan explaining their objectives, market opportunities, expected revenue, and intended use of financing.
Collateral
Some lenders require assets as security for a loan.
The value and suitability of collateral depend on the financing agreement.
Advantages and Disadvantages of Business Loans
Business loans can provide valuable financial support, but they also create responsibilities.
Advantages
Access to Capital: Businesses can obtain funds for important purchases, expansion, and operational requirements.
Business Ownership: Traditional loans generally allow business owners to retain their company ownership instead of exchanging equity for investment.
Flexible Financing Purposes: Depending on the loan agreement, financing can support inventory, equipment, working capital, and other business activities.
Potential Credit History Benefits: Responsible repayment may help establish or strengthen a business credit profile where the lender reports repayment information to relevant credit agencies.
Growth Opportunities: Additional funding can help businesses invest in projects that may increase productivity and revenue.
Disadvantages
Repayment Obligations: Businesses must repay borrowed funds according to the agreed schedule.
Interest Costs: Borrowing increases the overall cost of financing.
Collateral Risks: Secured loans may put business assets at risk if repayments are not made.
Eligibility Challenges: Startups and businesses with weak financial records may struggle to qualify.
Cash Flow Pressure: Regular loan repayments can reduce the money available for daily operations.
How to Choose the Right Business Loan
Selecting the right business loan requires careful financial planning.
Consider the following factors before making a decision.
1. Understand Your Business Requirements
Determine whether you need short-term working capital, equipment financing, expansion funding, or long-term investment capital.
Choose a financing option that matches the purpose.
2. Compare Interest Rates
Compare the annual percentage rate or equivalent total financing cost where available.
Consider all applicable charges rather than focusing only on the advertised interest rate.
3. Review Repayment Terms
Choose a repayment schedule that fits your expected business cash flow.
Avoid borrowing an amount that creates excessive monthly financial pressure.
4. Check Lender Reputation
Research the lender’s reputation, regulatory status, customer service, and financing conditions.
Read the complete agreement before accepting an offer.
5. Evaluate Collateral Requirements
Understand which assets may be pledged and what happens if the business cannot meet repayment obligations.
6. Calculate the Total Loan Cost
Estimate the total amount you will repay, including interest and fees.
This helps you determine whether the financing is financially reasonable.
Common Business Loan Mistakes to Avoid
Borrowing without proper planning can create financial problems.
Here are some mistakes business owners should avoid.
1. Borrowing More Than Necessary
Taking a larger loan than required increases interest costs and repayment responsibilities.
Calculate your actual funding needs before applying.
2. Ignoring Hidden Fees
Some loans include processing fees, administrative charges, late payment penalties, or early repayment fees.
Read the complete financing agreement.
3. Choosing the Wrong Repayment Period
A repayment period that is too short may create monthly cash flow pressure, while a longer period may increase total financing costs.
Choose terms that balance affordability and overall cost.
4. Using Business Loans for Unnecessary Expenses
Borrowed money should be used for its intended business purpose.
Avoid spending financing on activities that do not support business operations or financial objectives.
5. Failing to Prepare Financial Documents
Incomplete financial records can delay applications or reduce the chances of approval.
Maintain accurate accounting records and prepare required documentation in advance.
6. Ignoring Repayment Capacity
Never assume future sales will automatically cover loan payments.
Evaluate your current revenue, expenses, cash flow, and existing debt before borrowing.
Alternatives to Traditional Business Loans
A business loan is not always the best financing solution.
Depending on business requirements, entrepreneurs may consider alternative funding options.
Bootstrapping: Using personal savings or business revenue to finance operations.
Angel Investment: Receiving capital from individual investors in exchange for an agreed ownership interest or investment arrangement.
Venture Capital: Obtaining investment from professional firms that support high-growth businesses.
Crowdfunding: Collecting financial contributions through online platforms.
Business Grants: Applying for eligible financial support programs that generally do not require repayment.
Trade Credit: Arranging payment terms with suppliers that allow businesses to purchase goods and pay later.
Each option has different costs, eligibility conditions, risks, and ownership implications.
Frequently Asked Questions About Business Loans
1. What is a business loan?
A business loan is money borrowed by a company or entrepreneur from a financial institution or lender to support business activities. The borrower repays the amount according to agreed terms.
2. What are the main types of business loans?
Common types include term loans, small business loans, startup loans, equipment financing, business lines of credit, invoice financing, commercial real estate loans, and microloans.
3. Can I get a business loan for a startup?
Yes, some lenders and financing programs offer startup loans. However, eligibility may depend on the business plan, personal credit history, financial resources, and repayment capacity.
4. What credit score is required for a business loan?
There is no universal credit score requirement. Different lenders have different eligibility standards based on the financing product, loan amount, and overall financial profile.
5. Are business loans secured or unsecured?
Business loans can be secured or unsecured. Secured loans require collateral, while unsecured loans generally rely on financial history, creditworthiness, and repayment capacity.
6. How much money can I borrow for my business?
The available amount depends on the lender, business revenue, credit profile, financial position, collateral, and repayment capacity.
7. How long does business loan approval take?
Approval times vary. Some financing providers offer decisions within a few business days, while complex applications may take several weeks or longer.
8. Can a small business get a loan without collateral?
Some lenders provide unsecured business financing. However, eligibility requirements, interest rates, loan limits, and personal guarantee conditions may vary.
9. What documents are required for a business loan?
Common documents include business registration records, identification, bank statements, financial statements, tax records, business plans, and other documents requested by the lender.
10. Are business loans good for business growth?
Business loans can support growth when funds are used for productive investments and the company has sufficient repayment capacity. However, excessive borrowing can increase financial risks.
Conclusion
Business loans can provide important financial support to entrepreneurs, startups, and established companies. They allow businesses to access capital for expansion, equipment purchases, inventory, working capital, and other operational requirements.
However, choosing the right financing option requires careful planning and financial evaluation.
Before applying, understand your funding requirements, compare lenders, review interest rates, calculate total borrowing costs, and evaluate your repayment capacity.
A well-managed business loan can support sustainable growth, while unnecessary borrowing can create financial pressure.
Remember, successful business financing is not simply about obtaining money. It is about using borrowed capital wisely, maintaining healthy cash flow, and making responsible financial decisions.


One comment on “Business Loans: A Complete Guide to Financing Your Business”