
Introduction
Credit history is an important part of personal financial management. It shows how a person has managed borrowed money, credit cards, loans, and repayment responsibilities over time. Banks and financial institutions may review credit history when evaluating applications for financial products.
A positive credit history can help demonstrate responsible borrowing habits, while missed payments and unpaid debts may create difficulties when applying for credit. In this guide, we will explain what credit history is, why it matters, how to check it, and how to build a strong credit record.
What Is Credit History?
Credit history is a record of an individual’s borrowing and repayment activities. It may include information about credit cards, personal loans, home loans, payment records, outstanding balances, and credit applications.
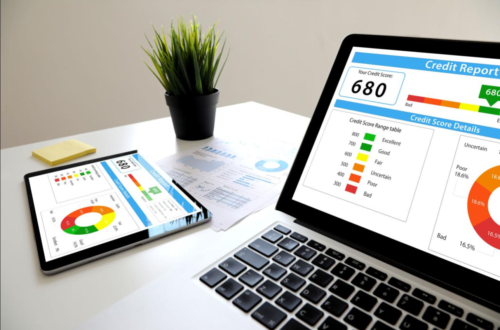
Credit reporting agencies collect information from participating lenders and financial institutions to create credit reports. Lenders may use these reports to understand a borrower’s financial behavior and assess credit risk.
How Does Credit History Work?
Credit history develops when financial institutions report information about your credit accounts and repayment activities to credit reporting agencies.
The general process works as follows:
- You open a credit account or receive a loan.
- The lender records your account details and payment activity.
- The lender may report relevant information to a credit bureau.
- The credit bureau updates your credit report.
- Lenders may review your credit history when you apply for new credit.
Reporting practices, information availability, and retention periods vary by country and credit bureau.
Information Included in a Credit History
A credit history may contain several types of financial information.
1. Personal Information
This may include your name, address, date of birth, and other identifying details used to match your credit records.
2. Credit Accounts
Your report may list credit cards, personal loans, auto loans, mortgages, and other reported credit accounts.
3. Payment History
Payment history shows whether you have made payments on time or missed payment deadlines.
4. Outstanding Balances
This section may show how much money you currently owe on reported credit accounts.
5. Credit Inquiries
Credit inquiries record certain requests to access your credit information. Some inquiries, such as those connected with new credit applications, may affect certain credit scores.
6. Negative Credit Information
Depending on local reporting rules, your credit history may include late payments, defaults, collections, or other negative account information.
Importance of Credit History
Credit history plays an important role in financial decisions.
- Loan Applications: Lenders may review your credit history before approving loans.
- Credit Card Approval: Financial institutions may use your borrowing and repayment record when evaluating credit card applications.
- Interest Rates: In some markets, a positive credit profile may help you qualify for more favorable borrowing terms.
- Financial Responsibility: Credit history demonstrates how you have managed previous credit obligations.
- Credit Opportunities: A well-maintained credit record may improve access to certain financial products.
- Financial Awareness: Reviewing your history can help you identify errors and unexpected accounts.
How to Build a Good Credit History
Building a positive credit history takes time and responsible financial habits.
1. Pay Your Bills on Time
Make loan and credit card payments before their due dates. Timely payments can help establish a positive repayment record.
2. Use Credit Responsibly
Borrow only what you can comfortably repay. Avoid using credit for unnecessary purchases or expenses beyond your budget.
3. Keep Credit Card Balances Manageable
Try to avoid using a large percentage of your available credit limit. Lower credit utilization may support a healthier credit profile.
4. Maintain Financial Records
Keep copies of loan agreements, payment receipts, bank statements, and other important financial documents.
5. Avoid Unnecessary Credit Applications
Apply for credit only when needed. Multiple applications within a short period may affect certain credit scoring models.
6. Monitor Your Credit Report
Review your credit report periodically to check whether your account details and payment records are accurate.
7. Repay Existing Debts
Make a realistic repayment plan and work toward reducing outstanding balances.
How to Check Your Credit History
You can review your credit history through an authorized credit bureau or reporting service available in your country.
Follow these steps:
- Identify the official credit reporting agency in your country.
- Visit its official website or approved service.
- Complete the required identity verification process.
- Request your credit report, if available.
- Review your accounts, payment records, and outstanding balances.
- Contact the credit bureau or lender if you find incorrect information.
Some agencies provide free reports, while others may charge a fee. Always use trusted and authorized services.
Common Problems That Can Damage Credit History
Several financial habits and unexpected situations may negatively affect credit history.
- Missing loan or credit card payments.
- Making payments after their due dates.
- Allowing debts to remain unpaid.
- Using too much available credit.
- Defaulting on loan agreements.
- Applying for multiple credit accounts unnecessarily.
- Ignoring incorrect information on credit reports.
- Taking loans without understanding repayment conditions.
How to Improve a Poor Credit History
If your credit history contains negative information, you can take practical steps to improve your financial position.
1. Review Your Credit Report
Identify late payments, outstanding balances, and incorrect information.
2. Correct Reporting Errors
If you find inaccurate information, contact the relevant credit bureau and lender through their official dispute procedures.
3. Pay Outstanding Debts
Create a realistic repayment plan and make payments according to your financial capacity.
4. Avoid Additional Unnecessary Debt
Limit new borrowing while working to manage existing financial obligations.
5. Make Future Payments on Time
Develop a consistent payment routine and use reminders to avoid missed deadlines.
6. Be Patient and Consistent
Accurate negative information may remain on credit reports for a period determined by local laws and reporting policies. Responsible financial habits can gradually improve your overall credit profile.
Credit History vs. Credit Score
Credit history and credit score are related, but they are different.
| Credit History | Credit Score |
|---|---|
| A record of borrowing and repayment activities | A numerical assessment based on credit information |
| Contains account and payment details | Summarizes credit risk using a scoring model |
| Shows past credit behavior | Helps lenders assess potential credit risk |
| May include loans and credit card records | Calculated using information from credit reports and other model-specific factors |
Credit History for Beginners
If you are new to borrowing, you may have limited or no credit history. This is sometimes described as having a thin credit file or being credit invisible.
You can start building a credit record through financial products that report account activity to authorized credit bureaus. Before opening an account, understand its fees, interest rates, eligibility requirements, and repayment responsibilities.
You do not need to borrow money unnecessarily to establish good financial habits. Managing existing obligations responsibly is more important than opening multiple accounts.
Common Credit History Mistakes
Avoid these mistakes to maintain a better credit record:
- Ignoring payment due dates.
- Borrowing beyond your repayment capacity.
- Not checking credit reports.
- Ignoring incorrect account information.
- Applying for unnecessary loans.
- Failing to understand loan agreements.
- Making only minimum payments without reviewing interest costs.
- Sharing personal financial details with untrusted websites.
Conclusion
Credit history is an important part of financial management because it shows how responsibly you have handled borrowing and repayment obligations. Paying bills on time, controlling debt, checking credit reports, and avoiding unnecessary borrowing can help build a positive credit record.
A strong credit history does not develop overnight. It requires patience, consistency, and responsible financial decisions. Understanding your credit history can help you prepare for future financial opportunities and manage your money more effectively.