
Introduction
Personal finance is the process of managing your money, including income, expenses, savings, investments, and financial goals. Good financial management helps individuals make better decisions, avoid unnecessary debt, and build a secure financial future.
Whether you are a student, employee, business owner, or family member, understanding personal finance can help you manage your money more effectively.
What Is Personal Finance?
Personal finance refers to how individuals manage their financial activities. It includes earning money, creating budgets, saving for emergencies, paying debts, and planning for future expenses.
The main goal of personal finance is to use money wisely while maintaining financial stability and achieving long-term financial goals.
Importance of Personal Finance
Managing personal finances is important because it helps people understand their financial situation and make responsible decisions.
Some major benefits include:
- Better Money Management: Helps you control your income and expenses.
- Financial Security: Prepares you for unexpected expenses and emergencies.
- Debt Reduction: Helps you avoid unnecessary borrowing and manage existing debt.
- Future Planning: Makes it easier to save for education, a home, retirement, and other goals.
- Financial Independence: Helps you become more confident and independent with money.
1. Create a Monthly Budget
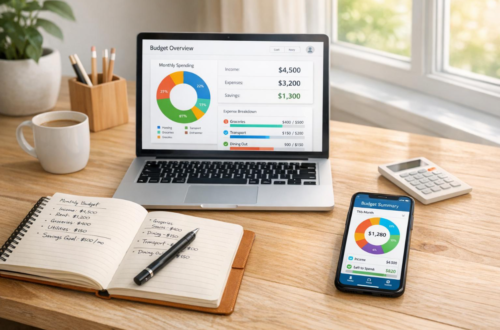
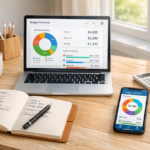
Creating a monthly budget is one of the most important steps in personal finance. A budget helps you understand how much money you earn and where you spend it.
Start by calculating your monthly income and listing all your expenses, including rent, food, transportation, bills, and personal purchases.
A simple budget can help you control spending and save more money each month.
2. Build an Emergency Fund
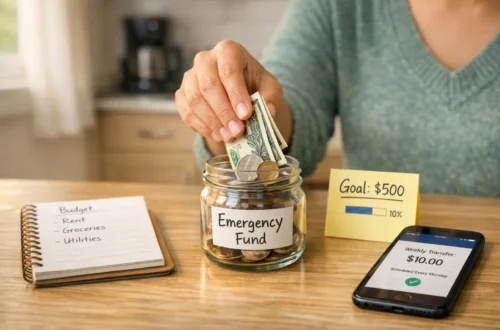
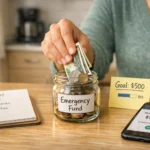
An emergency fund is money saved for unexpected situations such as medical expenses, job loss, urgent repairs, or other financial problems.
Try to save a small amount regularly until you have enough to cover three to six months of essential living expenses.
Keeping emergency savings can reduce financial stress and help you avoid borrowing money during difficult situations.
3. Manage Your Debt
Debt management is another important part of personal finance. Borrowing money without a proper repayment plan can create financial difficulties.
Make a list of your outstanding debts, interest rates, and monthly payments. Focus on paying high-interest debts first while continuing to make the required minimum payments on other debts.
Avoid unnecessary loans and credit card spending whenever possible.
4. Develop a Saving Habit
Saving money regularly helps you prepare for future needs and achieve your financial goals.
You can start by saving a small percentage of your monthly income. Set separate savings goals for short-term needs and long-term plans.
For example, you may save money for a new computer, education, a home, or retirement.
5. Understand Investing
Investing means putting money into financial assets with the goal of generating returns over time.
Common investment options include:
- Stocks and shares
- Mutual funds
- Government bonds
- Real estate
- Retirement accounts
Before investing, understand the risks, potential returns, fees, and time period involved. Never invest money you cannot afford to lose, and consider seeking advice from a qualified financial professional.
6. Plan for Retirement
Retirement planning helps you prepare financially for the time when you stop working.
Starting early can give your savings and investments more time to grow. Consider your future living expenses, healthcare needs, and available retirement savings options.
A good retirement plan can help you maintain financial independence later in life.
7. Monitor Your Financial Progress
Reviewing your financial situation regularly helps you understand whether you are achieving your goals.
Check your income, expenses, savings, debts, and investments every month. If your spending increases or your financial goals change, adjust your budget accordingly.
Using budgeting apps or a simple spreadsheet can make financial tracking easier.
Common Personal Finance Mistakes to Avoid
Many people experience financial problems because of poor money management. Some common mistakes include:
- Spending more money than you earn.
- Not creating a monthly budget.
- Ignoring emergency savings.
- Taking unnecessary loans.
- Making investments without proper research.
- Delaying retirement planning.
- Using credit cards without a repayment strategy.
Avoiding these mistakes can help you build better financial habits.
Tips for Improving Your Personal Finances
Here are some practical tips to improve your financial situation:
- Create a realistic monthly budget.
- Save money before making unnecessary purchases.
- Track your daily spending.
- Pay your bills on time.
- Reduce unnecessary expenses.
- Build an emergency fund.
- Learn about saving and investing.
- Set realistic financial goals.
Conclusion
Personal finance plays an important role in building a stable and secure future. By creating a budget, saving regularly, managing debt, and making informed financial decisions, individuals can improve their financial well-being. Start with small steps, develop responsible money habits, and review your progress regularly. Good financial planning today can help you achieve greater financial confidence and independence tomorrow.