
Introduction
Financial planning is an important part of managing money and building a secure future. It helps individuals understand their income, control expenses, save money, manage debt, and prepare for future financial goals. Whether you are a student, employee, business owner, or family member, having a financial plan can help you make better financial decisions.
With proper planning and consistent effort, you can improve your financial stability and work toward long-term financial independence.
What Is Financial Planning?
Financial planning is the process of organizing and managing your money to achieve personal and financial goals. It involves evaluating your current financial situation, creating a budget, building savings, managing debt, and planning for future expenses.
A good financial plan provides a clear direction for how to use your money wisely and prepare for unexpected financial challenges.
Importance of Financial Planning
Financial planning helps people manage their money more effectively and prepare for different stages of life.
Some major benefits include:
- Better Money Management: Helps you understand your income and expenses.
- Financial Security: Prepares you for unexpected financial situations.
- Savings Growth: Encourages regular saving habits.
- Debt Management: Helps control borrowing and repayment.
- Future Preparation: Supports goals such as buying a home or retirement.
- Financial Independence: Helps you make informed financial decisions.
1. Evaluate Your Current Financial Situation
The first step in financial planning is understanding your current financial position.
Calculate your monthly income, list your expenses, identify outstanding debts, and review your existing savings and investments.
This information helps you understand where your money goes and which areas need improvement.
2. Set Clear Financial Goals
Setting financial goals gives your financial plan a clear purpose.
Your goals can be divided into three categories:
- Short-Term Goals: Saving for bills, emergencies, or small purchases.
- Medium-Term Goals: Saving for education, a vehicle, or home improvements.
- Long-Term Goals: Planning for retirement, buying property, or building wealth.
Set realistic targets and decide how much money you need to save to achieve each goal.
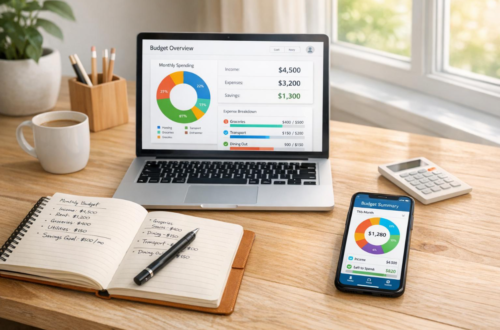
3. Create a Monthly Budget
A monthly budget helps you control your spending and manage your income.
Start by calculating your monthly earnings and dividing your money into different categories, such as housing, food, transportation, bills, savings, and personal expenses.
You can also follow the 50/30/20 budgeting rule as a starting point:
- 50% for needs.
- 30% for wants.
- 20% for savings and debt repayment.
Adjust these percentages according to your income and financial responsibilities.
4. Build an Emergency Fund
An emergency fund protects you from unexpected expenses, such as medical bills, job loss, and urgent repairs.
A common goal is to save enough money to cover three to six months of essential living expenses.
Start with small monthly contributions and gradually increase your savings until you reach your target.
5. Manage Your Debt
Managing debt is an important part of a successful financial plan.
Make a list of your loans, credit card balances, interest rates, and repayment dates. Prioritize high-interest debt while making the required payments on other debts.
Avoid unnecessary borrowing and try to pay your bills on time to maintain better financial control.
6. Plan Your Savings and Investments
Saving and investing can help you prepare for future financial needs.
Regular savings provide money for planned expenses, while suitable investments may help grow your wealth over time.
Common investment options include:
- Stocks and shares.
- Mutual funds.
- Government bonds.
- Real estate.
- Retirement savings accounts.
Before investing, research the risks, fees, and potential returns. Choose options according to your financial goals, risk tolerance, and investment period.
7. Consider Insurance Protection
Insurance can help protect your finances against unexpected risks.
Depending on your needs, you may consider:
- Health Insurance: Helps cover eligible medical expenses.
- Life Insurance: Can provide financial support to eligible beneficiaries.
- Car Insurance: Helps protect against covered vehicle-related losses.
- Home Insurance: Can provide protection against specified property risks.
Review insurance coverage carefully and understand its terms, exclusions, and costs before purchasing a policy.
8. Plan for Retirement
Retirement planning helps you prepare for life after employment.
Estimate your future living expenses and determine how much money you may need during retirement.
Starting early and saving consistently can give your money more time to grow. Review available retirement savings options and select those that match your financial situation.
9. Review and Update Your Financial Plan
Financial planning is an ongoing process. Your income, expenses, responsibilities, and goals may change over time.
Review your financial plan regularly to check your savings, investments, debt payments, and progress toward your goals.
Make adjustments whenever your financial situation changes.
Common Financial Planning Mistakes to Avoid
Avoid these common mistakes when managing your finances:
- Not having a clear financial plan.
- Spending more than you earn.
- Ignoring emergency savings.
- Taking unnecessary loans.
- Investing without proper research.
- Delaying retirement planning.
- Not reviewing your financial goals.
- Ignoring insurance and financial protection needs.
Avoiding these mistakes can help you build better financial habits.
Tips for Successful Financial Planning
Here are some practical tips to improve your financial planning:
- Set realistic financial goals.
- Create and follow a monthly budget.
- Track your income and expenses.
- Save money regularly.
- Build an emergency fund.
- Reduce unnecessary debt.
- Research investment opportunities.
- Review your financial progress regularly.
Conclusion
Financial planning is essential for managing money, achieving financial goals, and building a secure future. By creating a realistic budget, saving regularly, managing debt, and making informed investment decisions, you can improve your financial well-being. Start with small steps, remain consistent, and update your financial plan as your needs change. Good financial planning today can help create a more stable and confident tomorrow.